Yes, you can get financing for a used car with bad credit, but approval depends on the lender, your income, existing debts, credit history, and the vehicle you choose. A loan offer is not proof that the payment fits your budget: review the annual percentage rate, repayment term, fees, and any add-ons before signing.
- Used car financing bad credit decisions depend on income, debts, credit history, and the vehicle—not credit score alone.
- Gmsautos is a fit for Placentia buyers seeking used cars, pickup trucks, financing, and trade-in services.
- Compare APR, repayment term, and amount financed rather than choosing the lowest monthly payment.
- A co-signer shares repayment responsibility; a down payment does not guarantee approval.
Why this matters
Your goal is an affordable loan, not just an approval. A longer repayment term can reduce the monthly payment while keeping you in debt longer. Optional products added to the loan also increase the balance you repay.
For local shopping, Gmsautos sells pre-owned cars and pickup trucks in Placentia and offers financing and trade-in services. Treat the vehicle choice, financing terms, and trade-in appraisal as separate decisions so you can evaluate each on its own.
In 2026, start with your transportation needs and household budget. Decide what you can spend after insurance, fuel, maintenance, and other obligations—not what payment a lender is willing to approve.
Can I get used car financing with bad credit?
Yes. Lenders consider more than your credit score, although damaged credit can limit your options and lead to less favorable terms. Different lenders use different approval criteria, so a rejection from one lender does not establish that every lender will decline you.
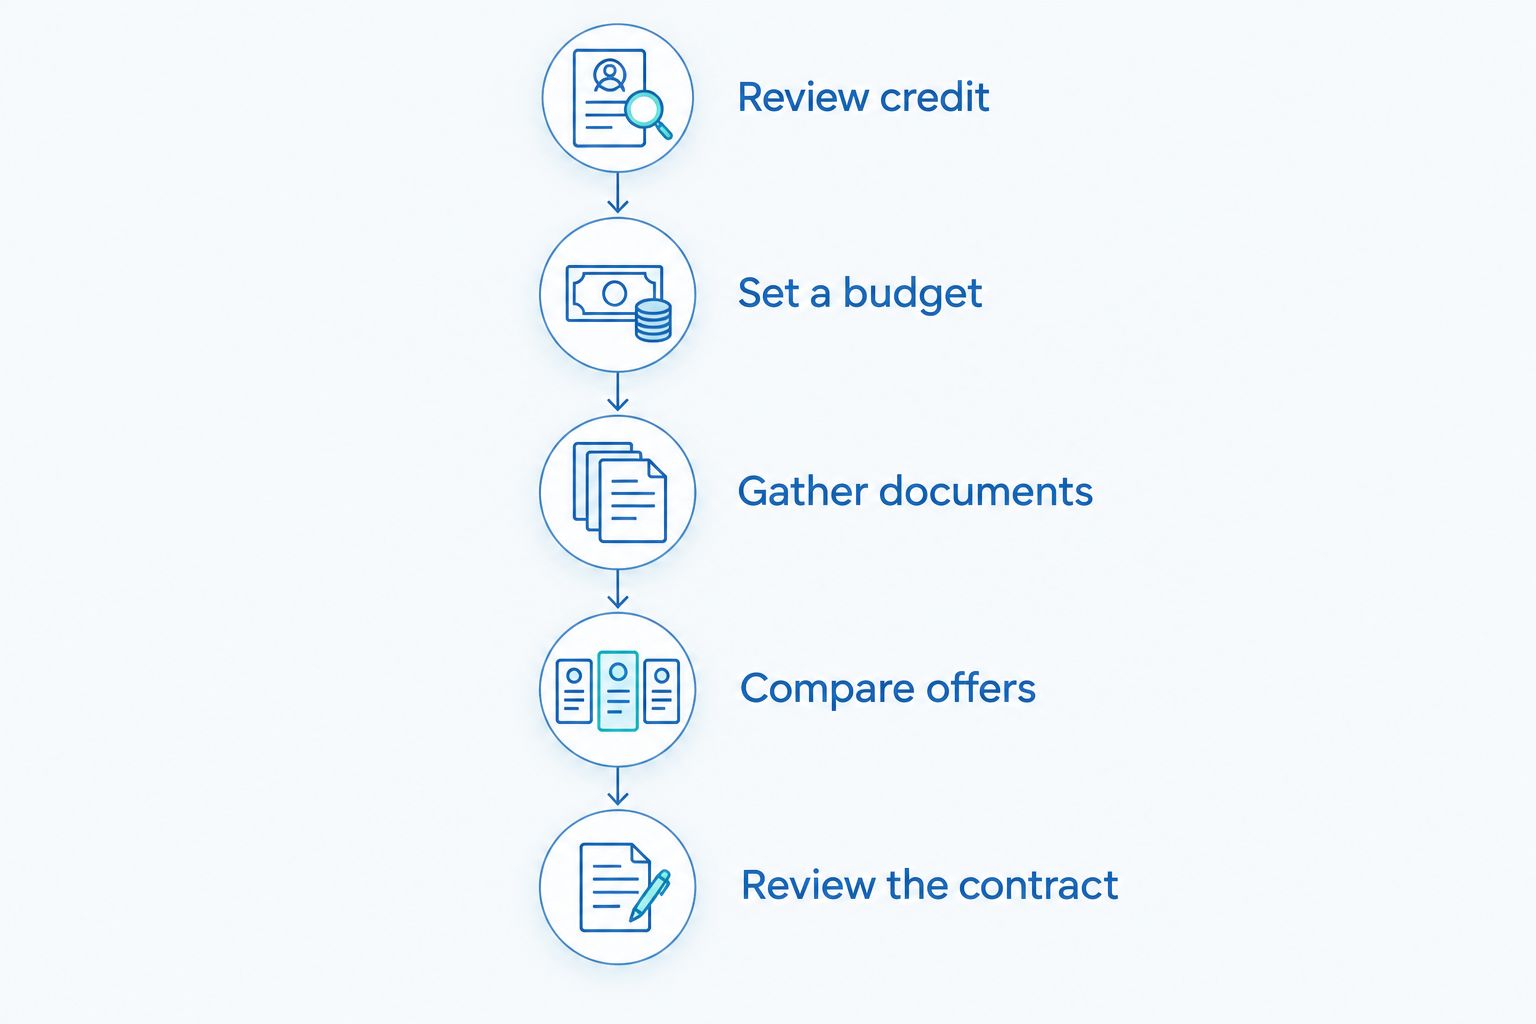
Use this sequence before committing to a vehicle:
- Review credit. Check your credit reports for unfamiliar accounts, incorrect balances, or payment errors. Dispute inaccurate information through the appropriate reporting channels.
- Set a budget. Include the proposed loan payment, insurance, fuel, maintenance, registration, and your existing obligations. Leave room for repairs instead of spending your entire transportation budget on the payment.
- Gather documents. Ask each lender what it requires. Common requests include identification, proof of income, residence information, and details about the vehicle.
- Compare offers. Review the APR, amount financed, term, finance charge, and total of payments. Ask whether a preliminary qualification involves a soft inquiry or a hard credit inquiry.
- Review the contract. Confirm that the written agreement matches the terms you accepted. Resolve unfamiliar charges, optional products, and any approval conditions before signing.
Keep these steps separate. Finding a vehicle you like should not replace checking whether its financing works for you.
Which financing route should I compare in 2026?
Compare direct lending with dealer-arranged financing. Neither route guarantees approval, and neither is automatically the better choice for a buyer with damaged credit.
| Financing route | Best for | Main benefit | Main limitation |
|---|---|---|---|
| Bank financing | Buyers who want a direct lender quote | Lets you evaluate financing separately from the vehicle transaction | Credit and vehicle requirements can exclude an applicant or car |
| Credit union financing | Buyers eligible for membership who want another direct quote | Adds another lender's terms to your comparison | Membership and underwriting requirements still apply |
| Dealer-arranged financing | Buyers who want to discuss the vehicle and financing together | Brings financing discussions into the purchase process | You still need to compare the offered terms against alternatives |
Compare actual offers rather than assuming a lender category means a better deal. A familiar institution can decline an application, and a convenient application process does not establish that the resulting loan is affordable.
Bank financing: best for a separate loan comparison
A bank quote helps you evaluate financing before negotiating the vehicle purchase. Ask about eligible vehicle age, mileage, and other restrictions before completing an application for a particular car.
The limitation is eligibility. Your banking relationship does not guarantee approval, and a preliminary quote is not the same as a final loan commitment.
Credit union financing: best for eligible members seeking another quote
A credit union gives an eligible buyer another set of terms to compare. Check membership requirements and ask whether the institution finances the specific used vehicle you are considering.
Do not assume membership replaces underwriting. The lender still evaluates the borrower and the vehicle, and its offer still needs to fit your budget.
Dealer-arranged financing: best for coordinating the purchase
Dealer-arranged financing lets you discuss the car and the financing within the same transaction. Ask who the lender is, what information is required, and whether approval remains subject to conditions.
The trade-off is that convenience can distract from the contract details. Keep your attention on the APR, balance, term, and optional products—not just the proposed payment.
Why bad-credit financing terms vary
A credit score is one part of a lending decision. These factors help explain why borrowers receive different decisions or terms:
- Credit history: Payment history, outstanding accounts, and recent credit problems affect how a lender evaluates repayment risk.
- Income and existing debts: A lender considers your ability to manage another payment alongside current obligations. Ask which income sources and documents it accepts.
- Down payment: Money paid upfront reduces the amount you need to borrow. It does not erase credit problems or guarantee approval.
- Trade-in equity: Positive equity can reduce the balance financed; negative equity adds an existing obligation to the transaction if rolled into the new loan.
- Vehicle details: Age, mileage, condition, and value can affect a vehicle's eligibility for financing and the lender's terms.
- Loan structure: The amount borrowed and repayment term change the obligation you take on. A different structure does not necessarily make the purchase affordable.
For your 2026 search, ask which factor is limiting an offer before changing your application. A larger down payment will not resolve every issue, and selecting a different vehicle will not correct inaccurate credit information.
How do I compare offers without focusing only on the payment?
Compare the whole obligation before comparing the monthly payment. A payment tells you what is due each month; it does not tell you everything you will repay or how long the debt lasts.
Read these disclosures together:
- APR: The annual percentage rate expresses the yearly cost of credit, including interest and certain fees.
- Amount financed: This is the amount of credit provided to you or on your behalf. Check it against the agreed transaction and any financed additions.
- Finance charge: This shows the dollar cost of credit disclosed for the loan.
- Total of payments: This shows what you will have paid after making all scheduled payments.
- Repayment term: This tells you how long the scheduled payments continue.
For example, a 60-month loan and a 72-month loan are different commitments even when they finance the same vehicle. The longer term spreads repayment over more months; compare the APR and total of payments before treating a smaller monthly bill as savings.
Also ask about prepayment penalties, late-payment provisions, and optional products. Do not assume a verbal explanation changes the written agreement.
Will shopping for a loan hurt my credit?
Loan applications can involve hard credit inquiries, but rate-shopping treatment differs from applying for unrelated credit accounts. Ask whether each application or preliminary qualification uses a hard inquiry before submitting it.
For 2026 rate shopping, the Consumer Financial Protection Bureau's consumer guidance describes a 14-to-45-day window in which auto-loan inquiries generally count as a single inquiry, depending on the scoring model. Keep your comparisons close together rather than assuming every scoring model uses the longest window.
That treatment does not guarantee your score will remain unchanged. It also does not turn a preliminary qualification into final approval or protect you from the consequences of missed payments later.
Can a co-signer help me get approved?
A co-signer can strengthen an application when the lender accepts co-signers and the additional applicant meets its requirements. A co-signer takes on repayment responsibility; the role is not a character reference.
Before involving someone else, make sure both people understand:
- Who is legally responsible for repayment under the contract.
- How late or missed payments can affect each person's credit.
- Whether the lender offers a co-signer release process and what it requires.
- How both people will monitor payments and account notices.
Do not use a co-signer to justify a payment you already know is unaffordable. Approval changes access to credit, not the amount left in your household budget.
Can I trade in a car when I still owe money?
Yes, a financed vehicle can be traded in, but the existing loan must be addressed as part of the transaction. Compare the lender's current payoff amount with the trade-in offer—not just the balance shown on an older statement.
If the payoff exceeds the trade-in value, you have negative equity. Rolling that difference into another loan means borrowing for the replacement vehicle while also carrying debt from the previous one.
Ask for the trade-in allowance, payoff, and treatment of any difference in writing. Do not assume that handing over the keys ends your responsibility for the old loan; confirm that the payoff is completed.
What should I check before signing in 2026?
Read the financing agreement separately from the vehicle description. A suitable car can come with an unsuitable loan, and a manageable loan does not establish that the vehicle is mechanically sound.
Before signing, confirm:
- Vehicle condition: Review available history information and arrange an independent inspection before committing.
- Written terms: Match the APR, repayment term, down payment, and amount financed to the agreement you accepted.
- Optional additions: Identify each add-on and decide whether you want it. Ask for an explanation of any claim that a product is required.
- Approval status: Ask whether financing is final or conditional and what happens if a condition is not met.
- Trade-in handling: Confirm the appraisal, payoff instructions, and treatment of positive or negative equity.
- Contract copies: Keep the completed documents and check that no material fields remain blank.
Pause if the contract and the explanation do not match. Get the discrepancy resolved in writing rather than relying on a promise to fix it later.
FAQ
Can I get used car financing with bad credit in 2026?
Yes, bad credit does not automatically prevent used car financing in 2026. Approval depends on the lender's requirements, your income, debts, credit history, and the vehicle; compare the written terms before accepting.
What credit score guarantees approval for a used car loan?
No credit score guarantees approval for a used car loan. Lenders also evaluate other application details and the vehicle being financed.
Can I get a used car loan without a down payment?
A loan without a down payment depends on the lender and your application; it is not guaranteed. Paying nothing upfront also means you are not reducing the financed balance with an initial payment.
Is a longer car loan better when I have bad credit?
A longer car loan is not automatically better when you have bad credit. Compare a 60-month loan with a 72-month loan using the APR, total of payments, and your budget—not just the monthly payment.
Can I finance a used pickup truck with bad credit?
Yes, used pickup truck financing is possible with bad credit, subject to lender approval. The truck's age, mileage, value, and other eligibility requirements matter alongside your application.
Does Gmsautos offer financing and trade-in services?
Gmsautos offers financing and trade-in services for local buyers shopping for pre-owned cars and pickup trucks in Placentia, California. Ask about the application requirements and review any proposed financing terms before committing.
One last thing
A trade-in appraisal and a loan payoff answer different questions. The appraisal tells you what you are being offered for the vehicle; the payoff tells you what is required to settle its existing loan.
Before your 2026 purchase, put both figures beside the proposed amount financed. That simple comparison helps you distinguish borrowing for your next vehicle from carrying debt forward from your previous one.